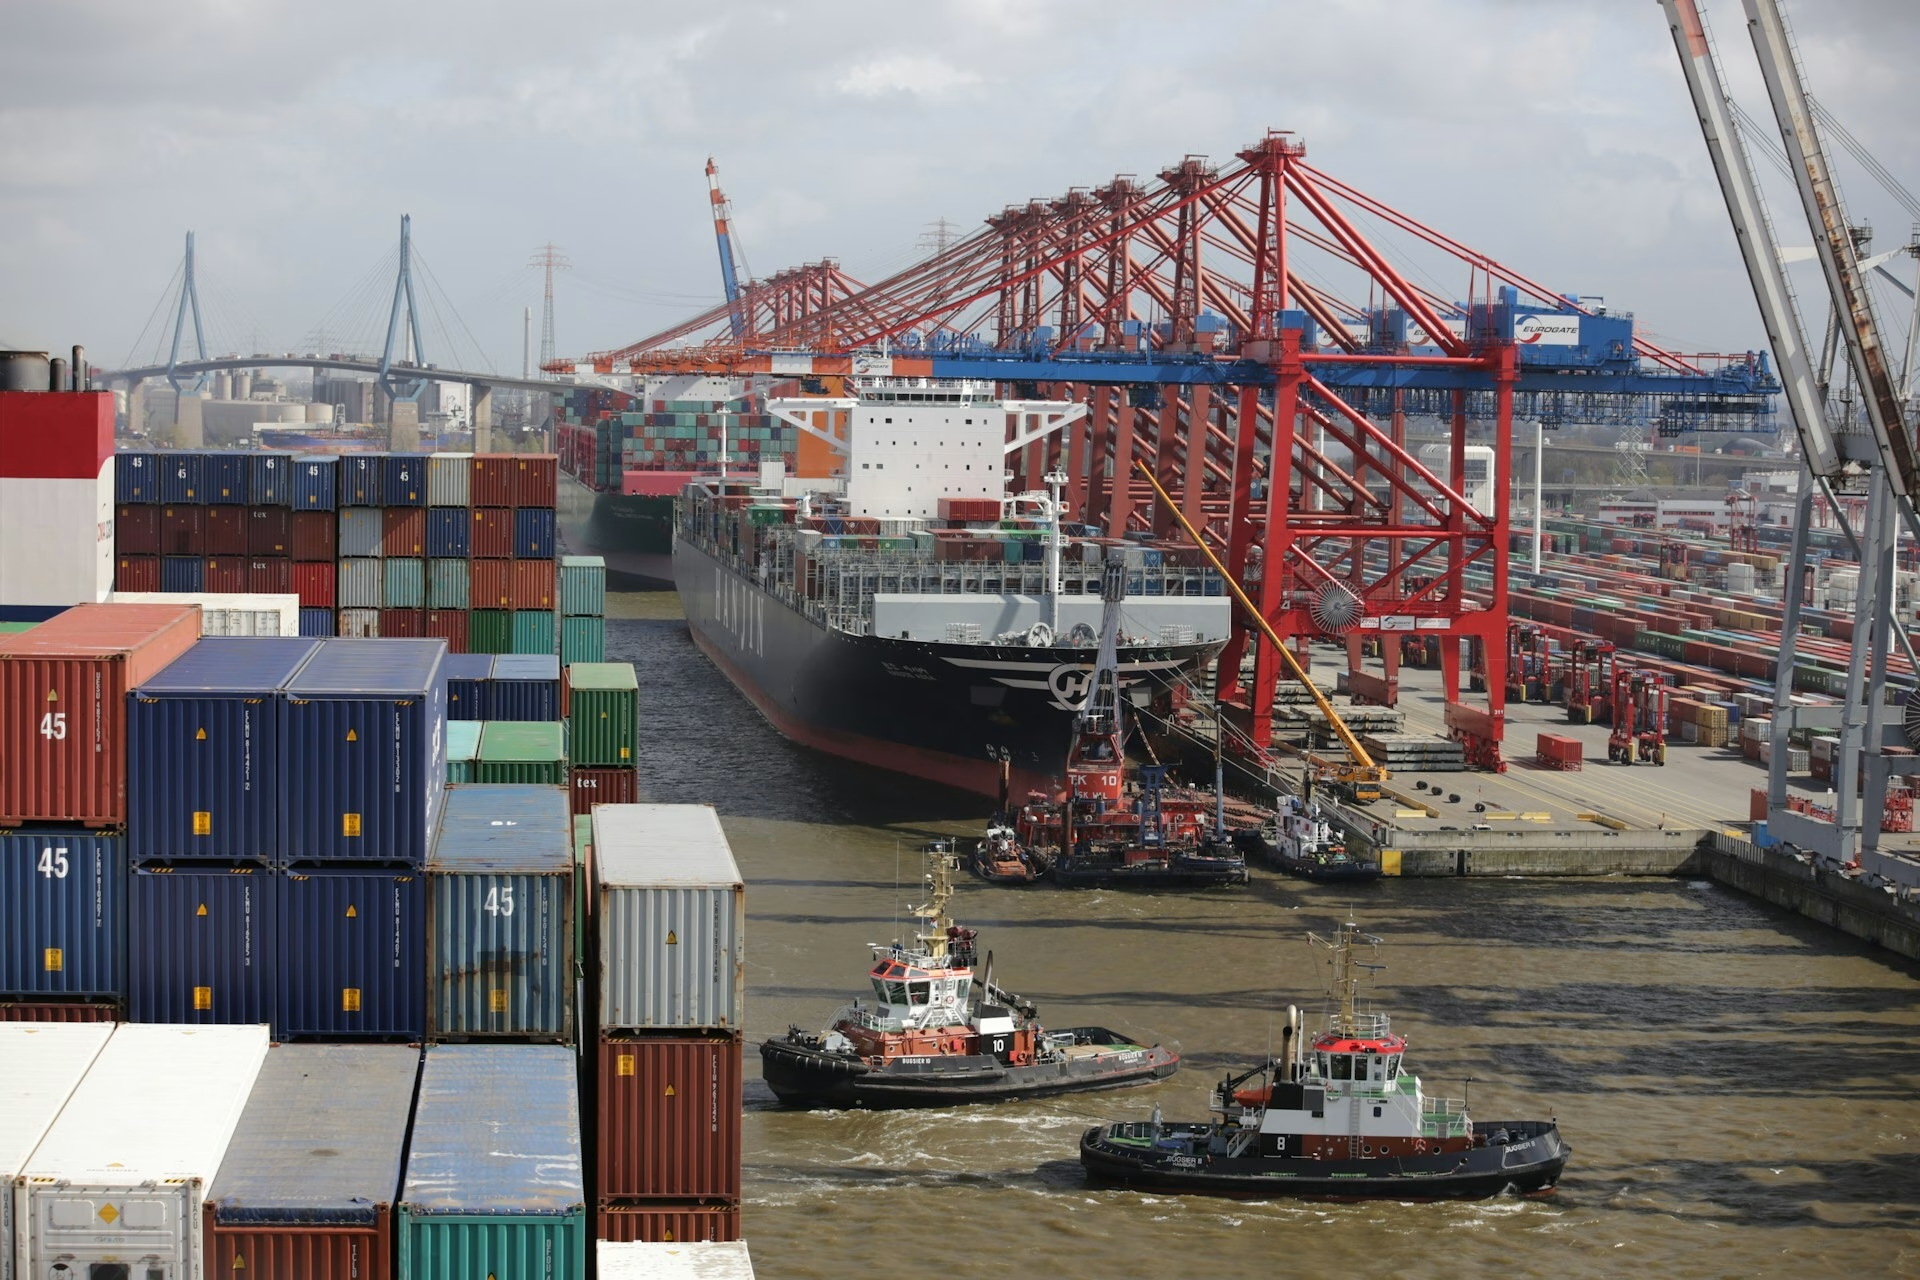
CBAM exposure starts with the goods presented to customs and their classification. A finished power transformer, a consignment of electrical steel and a shipment of spare parts can have different obligations. Treating them as one category produces unreliable cost estimates. So does treating a proposed extension as law already in force.
Regulatory review: 1 October 2026. This revision separates the rules currently applicable from the downstream extension under negotiation. It also updates the discussion of electrical steel safeguards and removes estimates that could not be tied to a defined shipment, emissions boundary or primary dataset.
For a utility ordering equipment with a long delivery schedule, the practical question is how to keep a purchasing decision valid as the rules change. For a Chinese manufacturer, it is how to provide the information an EU customer needs without presenting a general carbon footprint as a customs calculation. Both questions require a traceable product description, a documented supply chain and explicit assumptions about the import date.
What CBAM covers today: power transformers in scope and out
The definitive CBAM regime started on 1 January 2026. The applicable goods are identified by Combined Nomenclature codes in Annex I of Regulation (EU) 2023/956, as amended. The consolidated text checked for this review does not list heading 8504. A finished transformer correctly classified there is therefore outside the current Annex I product list. This statement concerns ordinary imports of the finished goods; special customs procedures require their own assessment. Consolidated regulation, Articles 2 and 6 and Annex I.
The presence of steel or aluminium inside a transformer does not, by itself, create a separate CBAM charge on those materials when the finished transformer is imported. Components imported separately must be assessed under their own classification. A tank, a radiator, a laminated core and a complete unit presented unassembled cannot safely be assigned codes from their material names alone. The equipment description and the customs rules governing the goods as presented matter.
| Commercial situation | Question to resolve | Evidence to retain |
|---|---|---|
| Finished transformer | Which code applies to the complete product, and is it listed at the date of import? | Technical specification, classification basis and applicable tariff record |
| Separately imported materials or parts | How is each imported item classified? | Shipment description, composition, invoice and customs classification |
| Unit shipped in several assemblies | Do the presentation and customs rules require treatment as a complete unit or separate goods? | Assembly drawings, shipment arrangements and classification advice |
| Future delivery under a present contract | Which assumptions must be revisited before import? | Regulatory review date, change clauses and allocated responsibilities |
The current exemption uses a cumulative annual threshold of 50 tonnes for the relevant CBAM goods imported by an importer. It is not a threshold applied independently to every shipment or purchase order. Electricity and hydrogen are excluded from this mass-based exemption. A company importing a mix of covered materials needs an aggregate view rather than a separate spreadsheet for each supplier. Commission guidance on the definitive regime.
Where the file stands now: Council and Parliament positions
The Commission’s December 2025 proposal, COM(2025) 989, would extend CBAM to selected downstream goods. Its annex includes the following entries within heading 8504. They describe the Commission proposal, not an adopted final product list.
| Code in the Commission proposal | Product range identified there |
|---|---|
| 8504 31 80 | A specified category of other transformers with capacity not exceeding 1 kVA |
| 8504 33 00 | Other transformers above 16 kVA and not exceeding 500 kVA |
| ex 8504 50 00 | Inductors containing steel or aluminium |
The liquid-dielectric subheadings 8504 21, 8504 22 and 8504 23 are absent from that proposal’s list, as are 8504 32 and 8504 34. This does not support a blanket distinction in which every distribution transformer enters scope and every transmission transformer is permanently excluded. The CN subdivisions do not map directly onto those two commercial labels. The proposal identifies carbon dioxide and perfluorocarbons as greenhouse gases for the listed entries; these are not precursor materials. COM(2025) 989 and its annex.
On 12 June 2026, the Council agreed a negotiating position that refined the downstream list and proposed annual reviews of further products. The European Parliament adopted amendments on 15 September 2026 and referred the file back for interinstitutional negotiations. Parliament’s summary describes a broader scope than the Commission originally proposed. These stages show why an analysis based only on the December annex needs a version date. They do not establish a final negotiated list. Council position; Parliament’s September vote.
1 January 2028 remains the proposed application date for the extension. A purchasing model can use it as a scenario, but should not present the original product list or that scenario as a final legal outcome. For a live import decision, the code must be checked against the legislation applicable when the goods are released for free circulation in the Union.
What this means for a long delivery schedule
A contract can distinguish three things: the obligations known at signature, the assumptions used to price later delivery, and the procedure for responding to a legal change. The supplier and buyer should agree who checks classification, who supplies emissions evidence and how a change in scope affects price and delivery. This is a procurement recommendation, not a prediction that a particular code will enter or remain outside CBAM.
Default values, actual emissions and verification
CBAM declarations can use actual verified emissions or the applicable default values. Independent verification applies to the actual-emissions route. It is therefore incorrect to say that every declaration requires a verifier to certify actual production data. It is equally incorrect to assume that missing information from one supplier automatically forces every input and the whole product onto one country default. The permitted treatment depends on the calculation method and the data concerned. Commission guidance on verification.
Verification planning still matters. An operator needs to identify the installations, production processes and reporting period covered by its calculation. The importer needs evidence that corresponds to the goods and the method used. A marketing declaration about renewable electricity or a company-wide carbon footprint cannot simply be substituted for the required product and installation information.
The default-value dataset also has a version history. Commission Implementing Regulation (EU) 2026/1740 corrected the values established under Regulation (EU) 2025/2621, and the Commission published an updated workbook in August 2026. A calculation should record the applicable legal act, product, origin, reporting year and dataset version. An older workbook may still open correctly while producing an obsolete result. Current legislation, default values and guidance.
Units and emissions boundaries need the same discipline. A value in tonnes of CO2 equivalent per MWh cannot be divided directly by a value per kWh: one MWh equals 1,000 kWh. After converting units, the comparison still needs matching years and definitions. A national electricity factor alone does not establish the CBAM exposure of a transformer, and indirect emissions are not included uniformly across every category of covered goods.
For a purchasing comparison, request a calculation that can be reconstructed. It should identify the imported good, quantity, applicable emissions method, evidence for the inputs, certificate-price assumption and adjustments. Avoid a single percentage described as the “CBAM rate on a transformer”: neither the purchase price nor the gross mass of the equipment determines the obligation on its own.
Trade defence and electrical steel
CBAM is only one part of the customs assessment. On 18 September 2026, the Commission announced provisional safeguard measures on grain-oriented electrical steel products, using tariff-rate quotas and price thresholds. The investigation had opened in March. The earlier description of these measures as merely a possible future development is therefore outdated. Commission announcement of provisional safeguards.
A safeguard analysis must use its own product scope, origin provisions and applicable measure. Being outside the current CBAM list does not answer that separate question. For a transformer project, review the imported electrical steel, laminations, cores and complete equipment against the relevant customs descriptions instead of assuming that a general statement about steel covers every shipment.
The commercial implication is a need to itemise the landed-cost model. Customs duties, safeguard exposure, CBAM obligations and supplier price changes arise through different mechanisms. Adding a generic carbon surcharge to the full equipment price can hide double counting; ignoring trade measures because the finished transformer is outside today’s CBAM list can miss an unrelated cost. Each line should state its legal or contractual basis.
What this means at the asset level
For the asset manager, emissions information can have uses beyond the customs declaration. A buyer may need it for a tender, a lifecycle assessment or its own reporting. Those requests should identify the intended use. A lifecycle footprint and a CBAM calculation can use related production records while applying different boundaries and accounting rules. Neither should be relabelled as the other.
Start the data request with the equipment and the procurement decision. Which unit is being offered? Which factories and material suppliers are involved? Does the evidence cover the proposed production route, or a different product made elsewhere? Who can explain a change in the material specification? These questions are useful before any sophisticated emissions model is built.
A practical supplier file can connect the equipment identifier, bill of materials, relevant installation information, emissions evidence and revision history. Access permissions should protect commercially sensitive records while allowing the responsible parties to review the evidence they need. Reusing a structured file across tenders can reduce repeated work, but maintaining it still has a cost when suppliers, production methods or regulatory requirements change.
Who actually pays: the importer-manufacturer split
The authorised CBAM declarant carries the declaration and certificate obligations. Commercial agreements should identify the importer and any indirect customs representative involved. A non-EU producer supplies relevant information but does not become the EU declarant simply because its product is exported. The first declaration and certificate surrender for 2026 imports are due by 30 September 2027. Commission operational guidance.
The party with the legal obligation and the party that ultimately bears a negotiated cost need not be the same. A buyer may seek a price adjustment, a supplier may price the cost of producing evidence, and either side may require contractual remedies for missing information. The outcome depends on the contract and bargaining position. It cannot be predicted from the regulation as an automatic discount on the manufacturer’s next order.
Article 9 provides for taking account of a qualifying carbon price effectively paid in a third country, subject to its conditions and supporting evidence. A comparison between headline Chinese and EU allowance prices is insufficient to calculate a deduction. It must relate to the declared emissions and the applicable rules. Regulation (EU) 2023/956, Article 9.
For manufacturers, the useful service is a documented explanation of what their data can support. For importers, it is an assessment that connects that evidence to the goods actually imported. Seetalabs’ technical and regulatory approach starts with that connection: equipment, production evidence and applicable requirements must agree before the cost calculation becomes meaningful.
Planning transformer procurement through 2030
A procurement model should carry separate scenarios for the present product scope and a future adopted extension. Keep the emissions assumptions separate from the scope assumptions: a more precise emissions estimate cannot resolve an uncertain classification or legislative outcome. Conversely, a confirmed code does not validate a supplier’s emissions data.
| Planning point | Work to complete | Assumption to revisit |
|---|---|---|
| At tender | Identify the goods, likely import arrangement and evidence available from bidders | Scope and classification used in each offer |
| At contract | Allocate responsibilities for data, verification where required and regulatory changes | Who bears a change in costs or documentation requirements |
| Before manufacture and shipment | Update the supplier file and check the law applicable to the planned import | Product list, customs measures, dataset versions and delivery date |
| During the reporting cycle | Reconcile imported quantities, evidence and declarations | Whether estimates agree with actual goods and records |
The distribution-versus-transmission label remains useful for engineering and market discussions, but it cannot carry the legal analysis. A product-specific register is more useful: code, description, origin, import arrangement, current scope, proposed changes and next review date. It gives purchasing teams a way to update the decision without rebuilding the entire analysis whenever a new text appears.
Frequently asked questions
Does the steel inside a finished transformer automatically attract CBAM?
No. Begin with the classification and scope of the imported goods. Materials incorporated into a finished product are not automatically treated as separate imports of those materials.
Does the proposed extension cover every distribution transformer?
The Commission proposal names specific CN entries. “Distribution transformer” is too broad to determine coverage, and the final negotiated list must be checked when adopted.
Can a supplier’s general carbon footprint be used as CBAM data?
Only evidence that satisfies the applicable calculation and verification requirements can support the relevant declaration. A broader corporate or lifecycle report may help collect inputs, but its label does not establish suitability.
Does using actual data always lower the cost?
No. Compare the applicable default with a properly calculated actual value and the relevant adjustments. Data quality improves the basis for a decision; it does not guarantee a favourable result.
What should be done before signing a long-term supply agreement?
Document the classification and scope assumptions, identify the evidence required, allocate responsibility for keeping it current and agree how regulatory changes will be handled. Recheck those assumptions before shipment.